Life Insurance Basics
Why People Get Declined or Rated Up
A plain look at the health and lifestyle factors that can lead to a decline or a higher rating on a life insurance application, and which ones can change over time.
The sheet in words
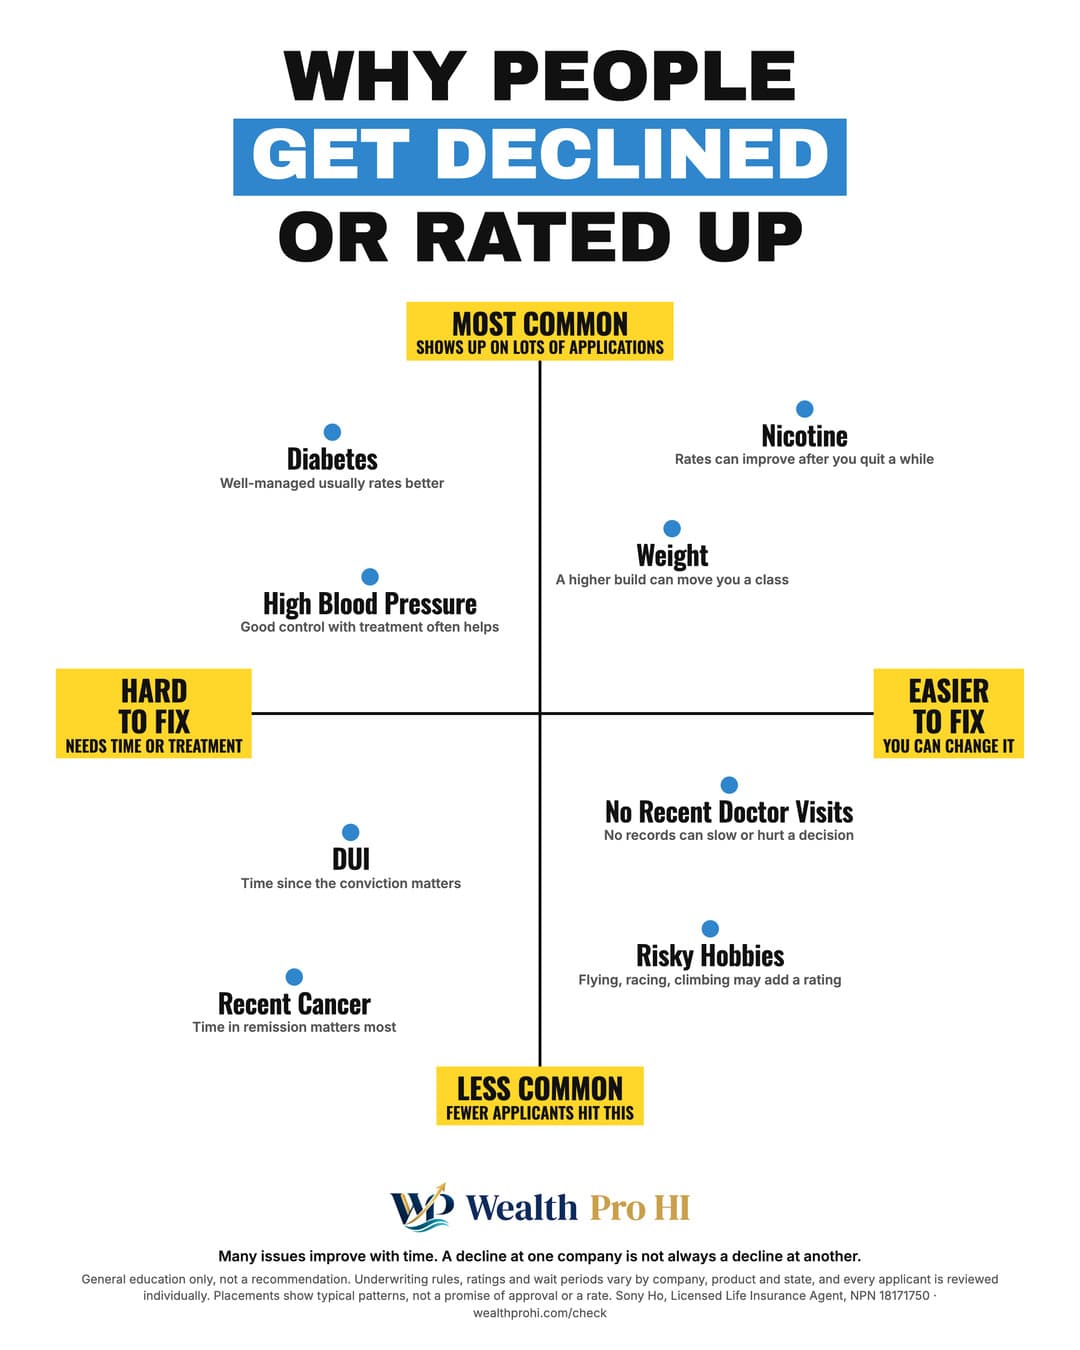
Up is most common (shows up on lots of applications); down is less common (fewer applicants hit this). Left is hard to fix (needs time or treatment); right is easier to fix (you can change it).
Diabetes
Well-managed usually rates better
Nicotine
Rates can improve after you quit a while
Weight
A higher build can move you a class
High Blood Pressure
Good control with treatment often helps
No Recent Doctor Visits
No records can slow or hurt a decision
Risky Hobbies
Flying, racing, climbing may add a rating
DUI
Time since the conviction matters
Recent Cancer
Time in remission matters most
Many issues improve with time. A decline at one company is not always a decline at another.
General education only, not a recommendation. Underwriting rules, ratings and wait periods vary by company, product and state, and every applicant is reviewed individually. Placements show typical patterns, not a promise of approval or a rate. Sony Ho, Licensed Life Insurance Agent, NPN 18171750 · wealthprohi.com/check
Next step
Answer a few quick questions about your situation. Free, and for Hawaii residents.
Take the free 60-second check